What is motor insurance?
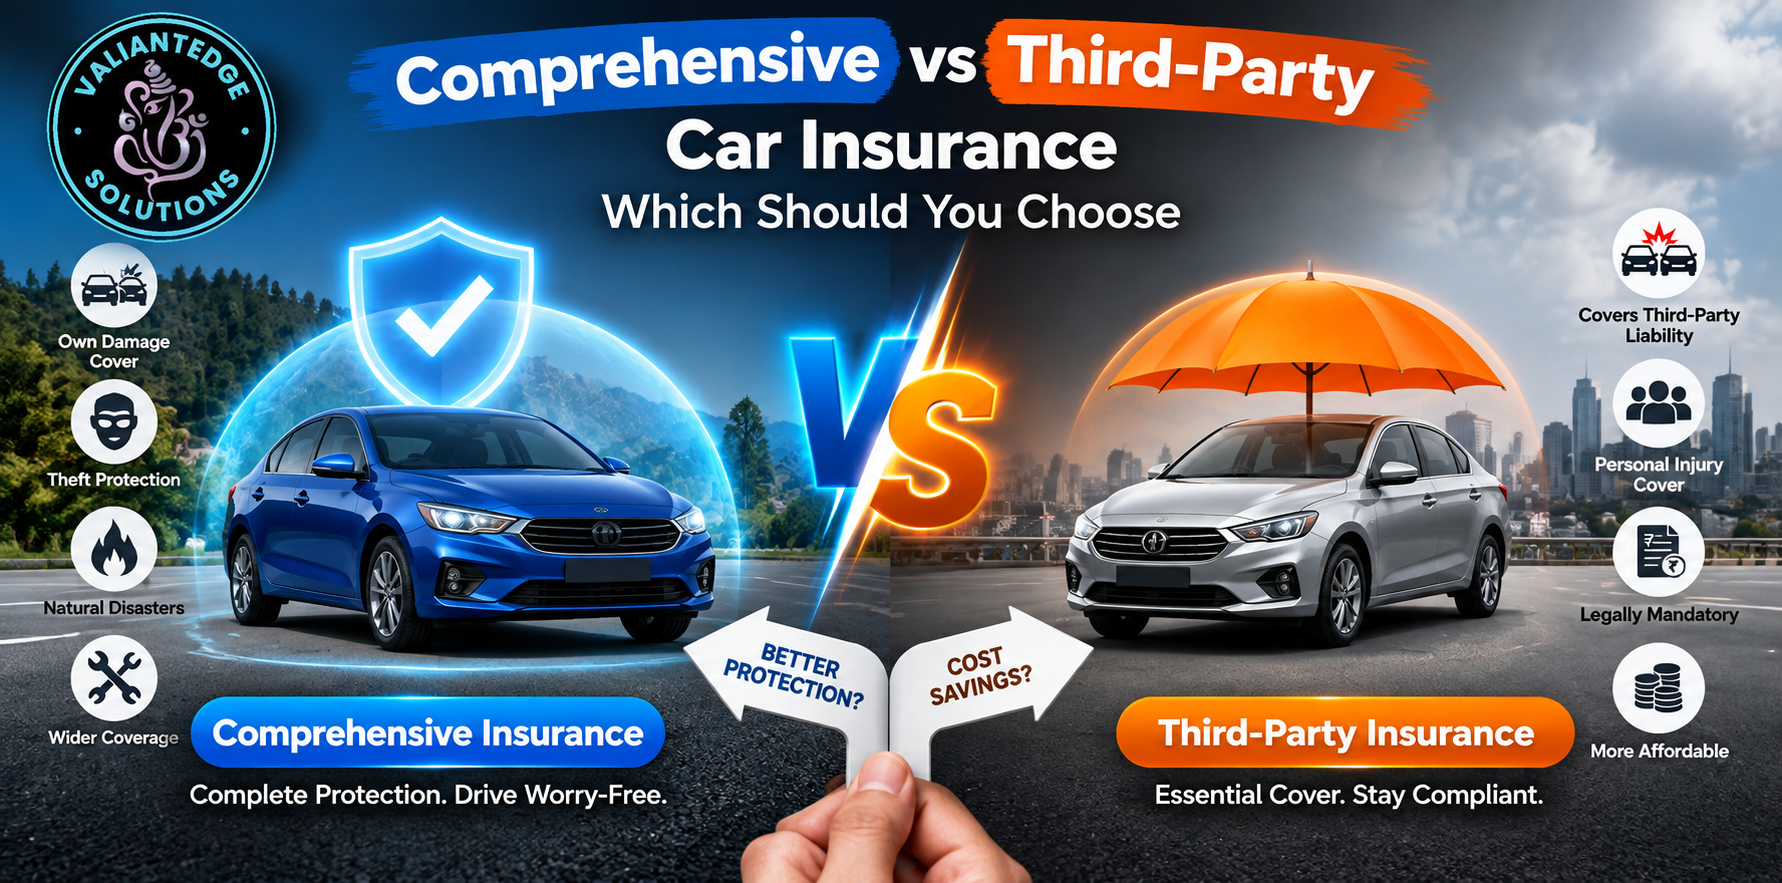
Motor insurance covers damage to your vehicle and your legal liability to others. Third-party cover is mandatory under the Motor Vehicles Act; comprehensive cover adds own-damage, theft and, with add-ons such as zero depreciation, pays the full cost of replaced parts. At Valiantedge Solutions we compare car insurance plans from 25+ IRDAI-licensed insurers, explain the fine print in plain language and stay with you through every renewal and claim.
This guide explains how car insurance works in India in 2026, who should buy it, how much cover is right, what it costs, and the mistakes that cause claims to fail. Everything below is written to answer the questions our advisors hear every day from families and business owners across Delhi, Noida, Ghaziabad, Gurugram, Faridabad and the rest of India.
Motor Insurance at a glance
| Feature | Detail |
|---|---|
| Legal minimum | Third-party liability cover, mandatory under the Motor Vehicles Act, 1988 |
| Penalty for driving uninsured | Rs 2,000 and/or up to 3 months imprisonment for a first offence |
| Comprehensive cover | Own damage + third party + theft + natural and man-made calamities |
| IDV | Insured Declared Value: the vehicle's current market value and the maximum theft/total-loss payout |
| No Claim Bonus | 20% after year 1, rising in steps to 50% after five claim-free years |
| Key add-ons | Zero depreciation, engine protect, roadside assistance, return to invoice, consumables |
| Mandatory long-term TP | 3 years for new cars, 5 years for new two-wheelers |
| Claim intimation | Report promptly; most insurers expect notice within 24-48 hours |
Who should buy motor insurance?
- Every vehicle owner; third-party cover is a legal requirement
- Owners of cars under 5-7 years old, where zero-depreciation pays for itself
- Commercial fleet owners needing goods-carrying and passenger liability cover
- Anyone whose NCB is about to lapse at renewal
It is usually not the right first purchase for:
- Nobody driving legally on an Indian road
Key benefits of motor insurance
Legal compliance
Avoids fines, vehicle seizure and licence consequences for driving uninsured.
Unlimited third-party injury liability
Third-party death and injury awards by tribunals have no monetary cap, which is the single largest uninsured risk a driver carries.
Zero depreciation pays the real bill
Without it, insurers deduct 30-50% depreciation on plastic, rubber and fibre parts, which is most of a modern bumper repair.
No Claim Bonus retention
Up to 50% off own-damage premium for claim-free years, transferable between insurers and vehicles.
Cashless garage network
Repairs settled directly at network garages, with pickup and drop at many.
How much motor insurance cover do you need?
Set IDV at genuine market value. Deflating IDV to shave a few hundred rupees off premium directly cuts your theft and total-loss payout. For vehicles under five years old, comprehensive cover with zero depreciation is almost always the right economics; beyond eight to ten years, a comprehensive-without-addons or third-party-plus-theft structure often makes more sense.
Our advisors run this calculation with you in a 15-minute call, using your actual income, loans, dependants and existing policies, then show side-by-side quotes so the number is grounded in what you will actually pay.
How to buy the right motor insurance plan: step by step
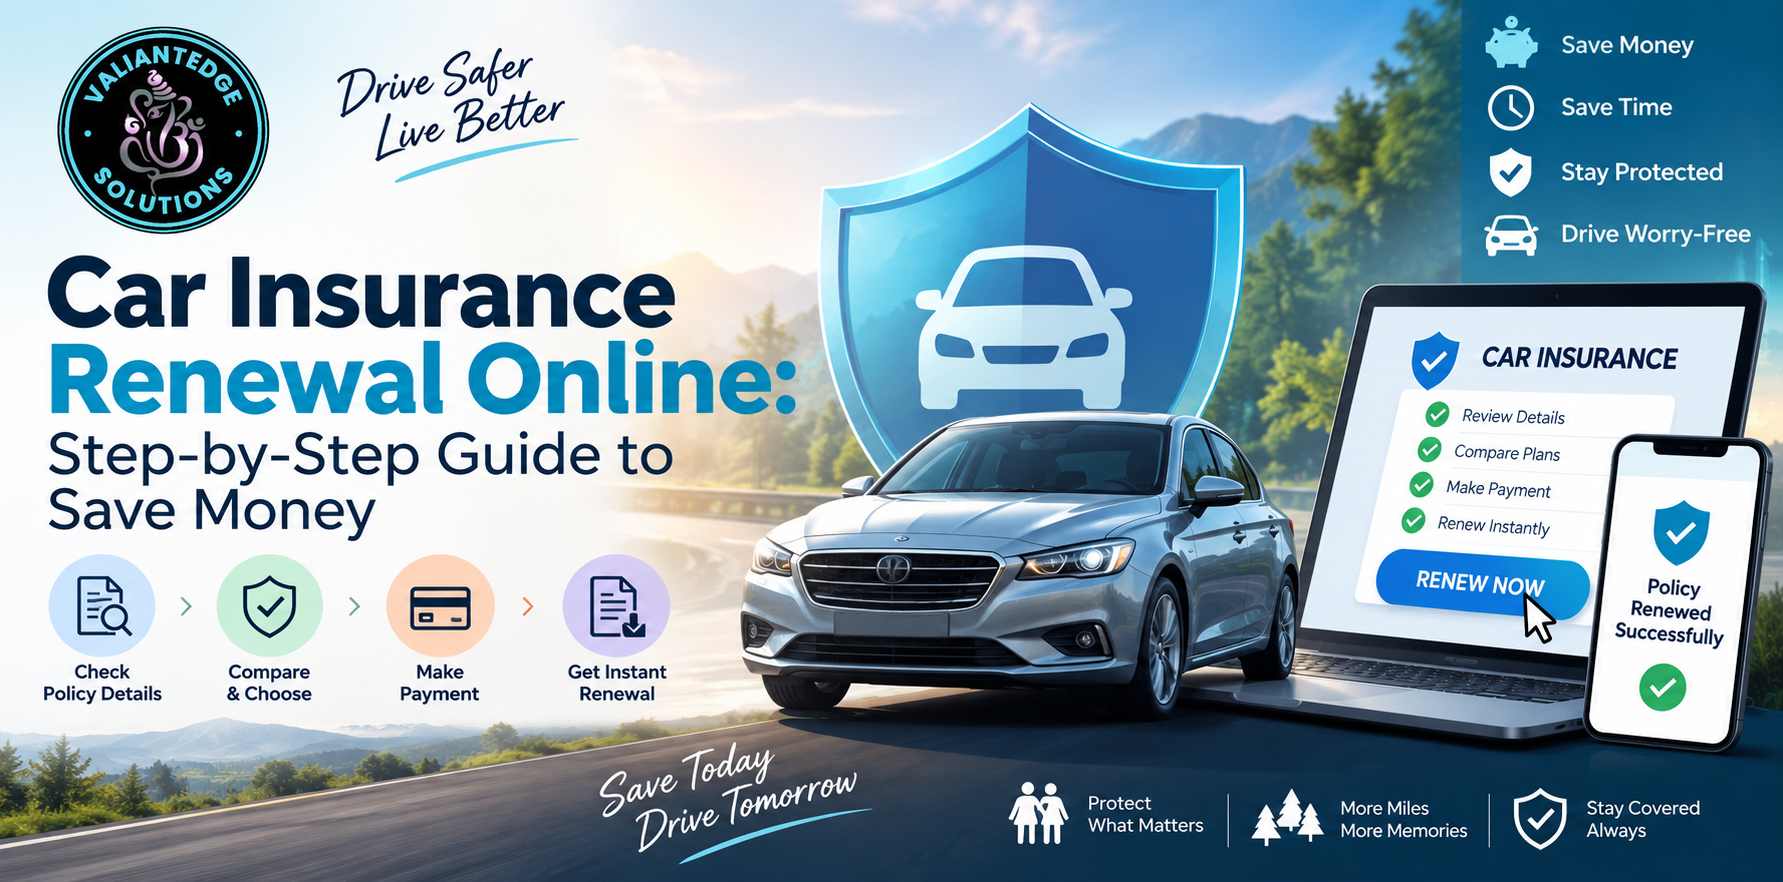
- Renew before expiry. A lapsed policy means an inspection before cover resumes and, after 90 days, total loss of accumulated No Claim Bonus.
- Set IDV honestly. It is your theft and total-loss payout, not a dial for cheaper premium.
- Pick add-ons by vehicle age. Zero depreciation and engine protect for newer cars; drop them as the vehicle ages and IDV falls.
- Carry forward your NCB. Switching insurers does not forfeit NCB. We retrieve the certificate from the previous insurer.
- At claim time, intimate first. Report to the insurer before authorising repairs. Unreported repairs are commonly rejected.
- Keep the paperwork. RC, driving licence, FIR for theft or third-party injury, and the repair estimate.
Why choose Valiantedge Solutions for motor insurance?
Valiantedge Solutions is an insurance advisory and distribution partner serving individuals, families and businesses across India. We are not tied to a single insurer, which means our recommendation for car insurance is based on your profile, not on commission. Every policy we place comes with dedicated claim assistance, renewal reminders and a named advisor you can call.
- Unbiased comparison across 25+ life and general insurers, with IRDAI claim settlement data shown alongside premium.
- Plain-language explanation of waiting periods, exclusions, riders and tax treatment before you sign.
- Claim support that stays with you: we handle documentation and insurer follow-up when you need it most.
- Doorstep, phone or video consultation at a time that suits you, in Hindi or English.
- Transparent pricing: you pay exactly the insurer's premium, nothing extra for advice.
Motor Insurance services across India
We help clients buy and manage car insurance in Delhi, Noida, Ghaziabad, Gurugram, Faridabad, Mumbai, Pune, Bengaluru, Hyderabad, Chennai, Kolkata, Ahmedabad, Jaipur, Lucknow and Chandigarh, as well as hundreds of other cities and towns. Local knowledge matters: hospital networks, garage networks, regional claim turnaround and even premium zones vary by city, and our advisors factor that into every recommendation. Use the location pages on this site to find car insurance guidance for your city, or simply request a callback and we will connect you with an advisor who knows your area.
Frequently asked questions about motor insurance
Is third-party car insurance enough?
It is the legal minimum, but it pays nothing for your own vehicle. If your car is stolen or written off, third-party cover returns zero. For any vehicle you could not comfortably replace from savings, comprehensive cover is the sensible choice.
What is IDV and why does it matter?
Insured Declared Value is your vehicle's current market value and the maximum you receive if it is stolen or declared a total loss. Lowering IDV reduces premium slightly but reduces your payout proportionally.
What does zero depreciation cover actually do?
Normally insurers deduct depreciation on replaced parts: 50% on plastic and rubber, 30% on fibreglass. Zero depreciation waives that deduction, so the insurer pays the full part cost. On a modern car this frequently doubles the settled amount.
Will I lose my No Claim Bonus if I change insurer?
No. NCB belongs to you, not the insurer, and transfers on production of the previous policy and claim history. It is also transferable to a new vehicle.
My policy expired last month. What happens?
Driving is illegal and any accident is uninsured. Cover can be restored, usually after a vehicle inspection. If the lapse exceeds 90 days you lose accumulated No Claim Bonus entirely.
Does motor insurance cover flood damage?
Comprehensive policies cover flood and other natural calamities for the vehicle itself. Engine damage caused by trying to restart a waterlogged engine is excluded unless you hold an engine protect add-on, a common and expensive claim rejection in monsoon cities.
Get a free motor insurance quote today
Share your name and phone number in the form on this page and a Valiantedge Solutions advisor will call you back within one working hour with a personalised comparison. There is no fee, no obligation and no spam. You can also reach us on WhatsApp or call the number at the top of this page.